Should You Act Before The Budget?
A calm guide to what’s confirmed, what’s rumour, and what to do about it
3 October 2026
You Don’t Need To Panic About The Budget
People pulled a record £91 billion from their pensions in the last year, up more than a fifth from the year before. A lot of that rush is fear, not planning: fear that the Budget on 28 October will change the rules before anyone’s had a chance to prepare.
Here’s what’s worth knowing before you make any decisions: some of what’s being discussed is already locked in and confirmed. Some of it is still just a rumour doing the rounds online. Telling the two apart is the whole game, and that’s exactly what this post is for.
No scare tactics, no “act now before it’s too late.” Just a clear, honest look at what’s actually true, what to do about it, and what you can safely ignore.
What’s Already Confirmed
Start here, because this part doesn’t require any guessing. The following have already been set out by the government in writing, ahead of the Budget:
- Your Cash ISA allowance stays at £20,000 if you’re 65 or over. From April 2027, people under 65 will see their Cash ISA limit cut to £12,000. However, anyone 65 and older keeps the full £20,000. This is one of the rare moments where the rules are written specifically to protect people of our age.
- Unused pension pots will count towards inheritance tax from April 2027. If you have a defined contribution pension pot you don’t draw down, money left in it when you die will, from that date, be counted as part of your estate for inheritance tax. This has been confirmed; it isn’t a rumour.
- The earliest age you can normally access a private pension rises from 55 to 57 in April 2028. If you’re already over 57, this doesn’t affect you. If you’re younger and were planning to access a pension early, it’s worth knowing now rather than finding out later.
None of this is brand new, but it’s worth having all three in one place, because they’re the facts everything else gets built on.
The Rumour vs The Rule
This is where it gets messier, and where much of this week’s panic is coming from.
The rumour: the State Pension triple lock could be scrapped from 2030. A headline did the rounds this week suggesting the triple lock might be replaced with a flatter, earnings-linked rise after 2030. We went looking for where this came from, a government announcement, a formal proposal, anything official, and found nothing. The government’s confirmed position is still that the triple lock holds until April 2030. Until there’s an actual announcement, treat this as speculation, not something to plan around.
The rumour: the tax-free lump sum could be cut in this Budget. This fear is driving a lot of this year’s record withdrawals, with people taking their 25% tax-free lump sum now, just in case it’s reduced on 28 October. Commentators are discussing it as a genuine possibility, but it is not confirmed. Nobody outside the Treasury knows what’s actually in this Budget yet.
The rule of thumb: if you can trace a claim back to an actual government announcement or an official GOV.UK statement, it’s confirmed. If it traces back to “sources say,” a single news outlet, or someone’s educated guess about what a politician might do, it’s still a rumour, no matter how confident the headline sounds.
Should You Act Now, Or Wait?
Here’s an honest answer: for most people, rushing to withdraw money because of a headline isn’t a plan; it’s a reaction.
Some financial firms are running adverts right now telling you to “act before the Budget.” It’s worth asking why. Pushing you to withdraw or move money now, while nothing is confirmed, benefits them more than it benefits you in many cases. Taking your tax-free lump sum early because you’re scared of losing it, when that isn’t actually confirmed to be at risk, could mean paying tax you didn’t need to, or losing out on growth your pension would otherwise have had.
That doesn’t mean do nothing. It means the decisions worth making now are based on what’s already confirmed, not on what might happen in five weeks. If a decision only makes sense because of a rumour, it can wait until 28 October, when you’ll know for sure.
What To Actually Do This Week
A short, calm to-do list: nothing urgent, nothing to panic about:
- ☐ Check your own age against the confirmed changes above. The ISA allowance split and the pension age rise affect only certain ages, so work out whether they apply to you.
- ☐ If you’re considering withdrawing a pension lump sum, speak to a regulated financial adviser or use Pension Wise’s free guidance service before you decide, not a headline.
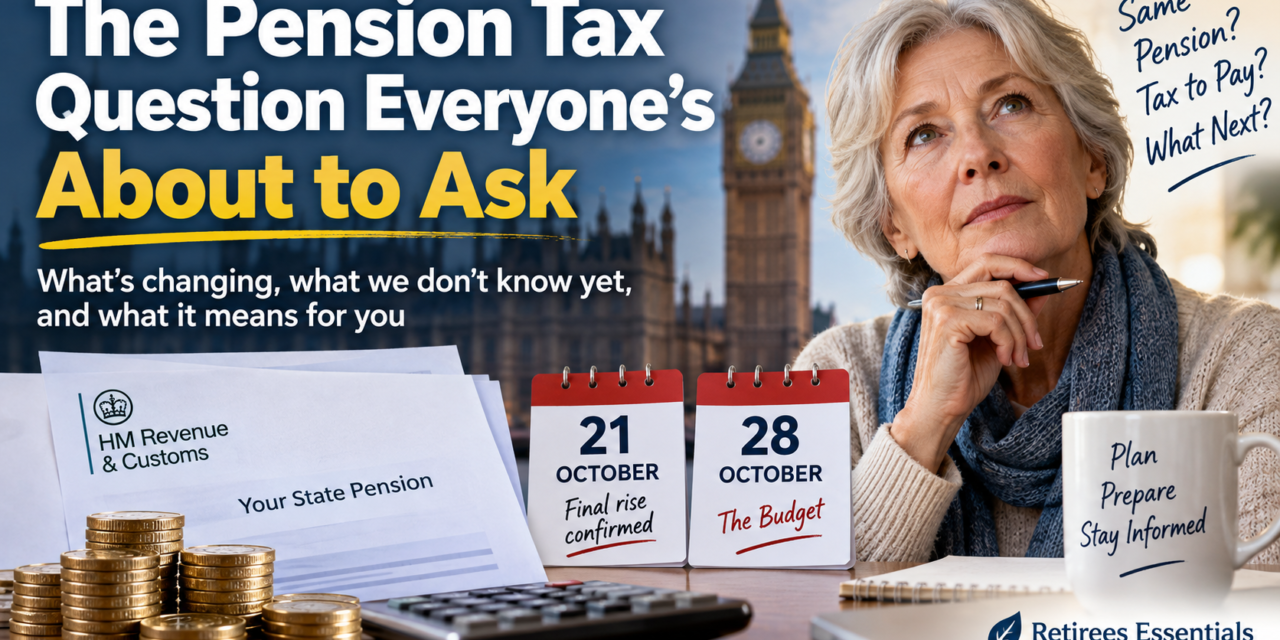
- ☐ Mark 21 October (the next inflation figure, which affects next year’s State Pension rise) and 28 October (the Budget itself) in your calendar, so you know exactly when real news will land.
- ☐ Be sceptical of anything that tells you to act “before it’s too late” without naming a specific, confirmed change. That phrase is a sales technique, not a fact.
That’s it. You don’t need to do anything more than that right now.
The Bottom Line
A record £91 billion left pensions last year because people were scared, not because they had a clear plan. You don’t have to be one of them.
The facts that matter are simple: a few things are genuinely confirmed, a few headlines are still just noise, and the real news lands on 21 and 28 October. Until then, the calmest, most sensible thing you can do is exactly what you’re doing right now: getting informed from a source that tells you honestly what it knows and what it doesn’t.
We’ll keep updating as the real news comes in. No panic required.
The facts are simple: a few things are confirmed, a few headlines are still just noise, and the real news lands on 21 and 28 October. Until then, the calmest, most sensible thing you can do is exactly what you’re doing right now — getting informed from a source that tells you honestly what it knows and what it doesn’t.
We’ll keep updating as the real news comes in. No panic required.
Where This Comes From
Real Progress Beats Perfect Plans
Inside Marketing with Martin, you’ll meet retirees making steady, realistic progress, not chasing hype or overnight success. We celebrate small wins and encourage you to learn at your own pace.
👉 Join Marketing with Martin and move forward with support, not stress.